

Peace
How to Set Financial Goals You'll Actually Keep
Money goals often fade because they're vague, borrowed or missing a plan for the hard moments. Here's a research-backed way to set one goal, plan for obstacles and see your progress.
Not opening the banking app isn't laziness. It's your brain protecting you from a bad feeling. Here's why money avoidance happens, what it quietly costs, and a gentle way to start looking again.
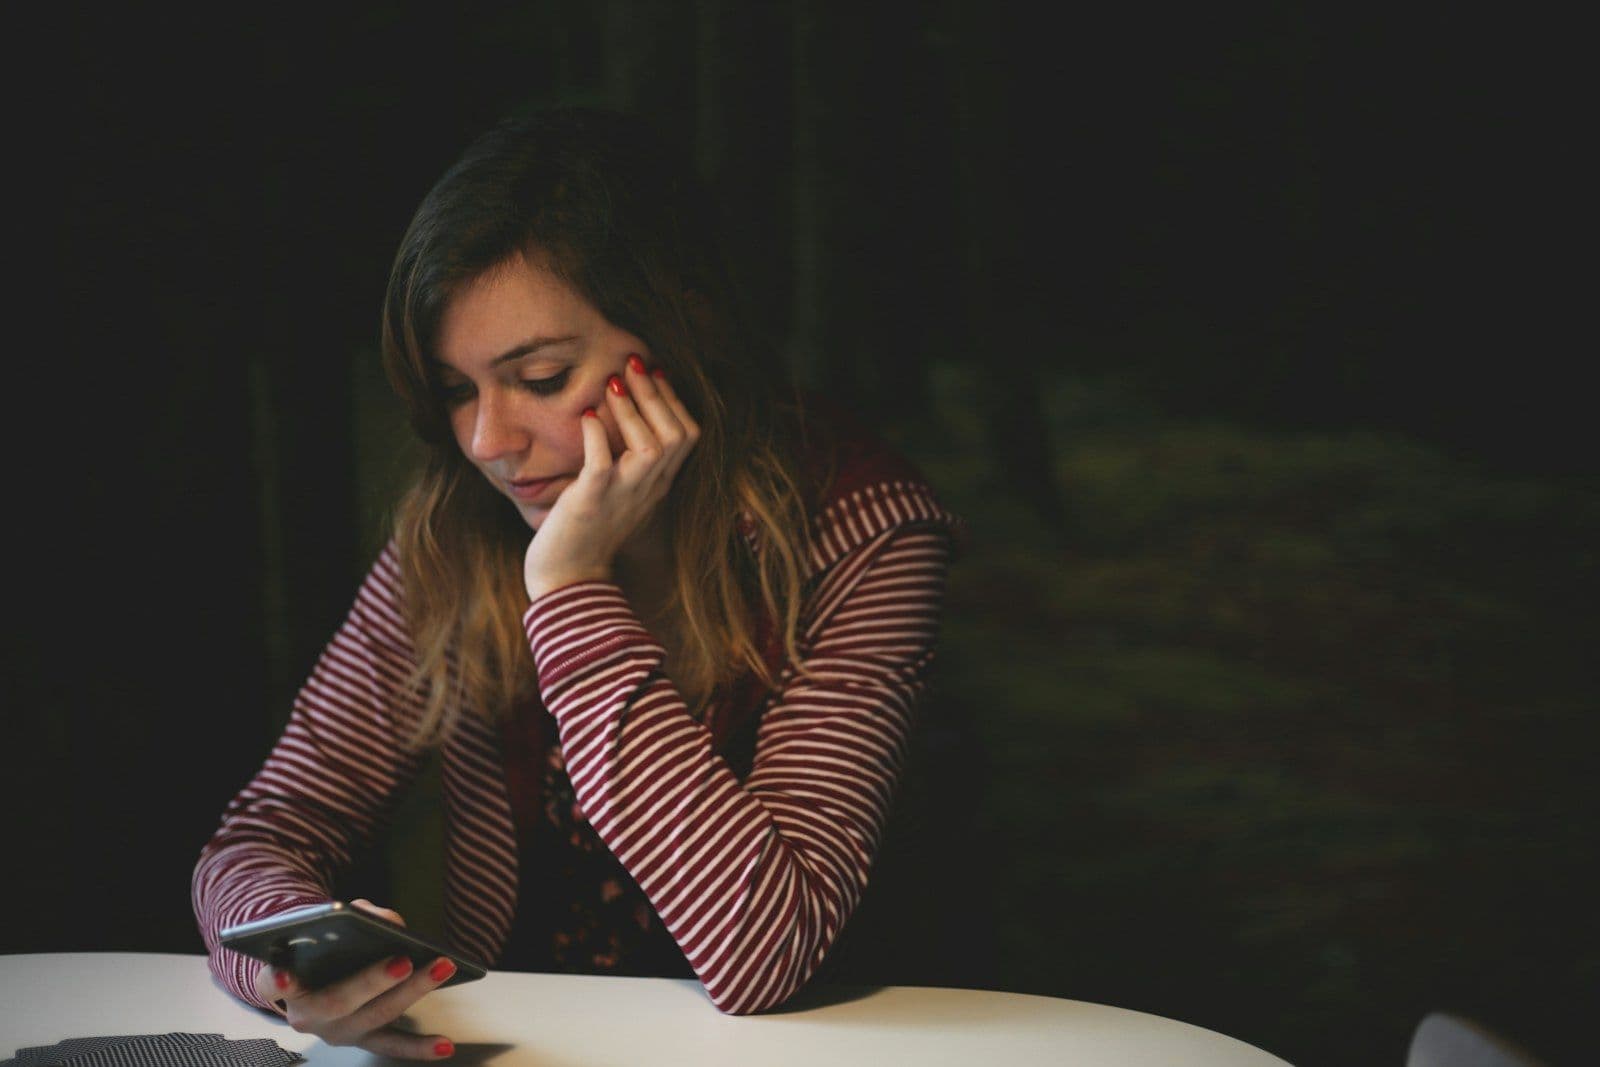
The banking app sits on your phone's second screen, where you don't have to see it. There's an envelope from the credit card company on the counter, still sealed. You have a rough idea of your balance, and you'd rather keep it rough.
If this sounds familiar, you're not unusual and you're not irresponsible. You are doing something human brains do all the time: looking away from information that might hurt.
Researchers have a name for it: the ostrich effect. In one study of investors' daily account logins, logins fell by 9.5% after the market went down. When the news was likely to be bad, people simply looked less.
Money avoidance is the same pattern in everyday life. Leaving statements unopened. Not checking a balance before paying. Putting off a bill until the late notice arrives. Psychologists who study money beliefs list money avoidance as one of four common "money scripts," the beliefs about money we absorb early and often carry without noticing.
Understanding why it happens is the first step to changing it gently, without forcing yourself and without shame.
Key takeaway
Avoiding your bank account is a common, understandable way to protect yourself from a bad feeling. It is not laziness.
Avoidance works, briefly. That is the problem.
When you think about checking your account, you feel a small spike of dread. When you decide not to check, the dread drops. Your brain notices that relief and learns a lesson: not looking makes me feel better. Each time you avoid, the lesson gets a little stronger.
A few other forces usually join in:
None of these is a character flaw. They are protective habits that have outlived their usefulness. If you also feel broke no matter what the numbers say, our guide to money dysmorphia looks at that side of the picture.
Key takeaway
Avoidance brings instant relief, and that relief trains the habit. Shame and uncertainty make it stronger.
The relief of not looking is real, but it comes with a delayed bill.
Practical costs. Late fees, overdraft charges, subscriptions you forgot to cancel, a fraudulent charge you didn't catch in time, interest that kept growing on a balance you didn't want to see.
Emotional costs. This is the part people don't expect. Avoidance doesn't make money worry go away. It moves it into the background, where it hums all day as a low-level dread that is hard to switch off. Financial anxiety often shows up in the body as poor sleep, a tight chest or stomach trouble.
The loop. The less you look, the more uncertain things feel. The more uncertain they feel, the scarier looking becomes. Breaking the loop doesn't require courage all at once. It requires looking in doses small enough to feel safe.
Key takeaway
Avoidance lowers stress today and raises it later, through fees, missed problems and a constant background hum of worry.
Psychologists call one way out of avoidance gradual exposure: approaching the uncomfortable thing in small, manageable steps until it stops feeling threatening. You can apply the same idea to your money.
Each step below is a rung on a ladder. Stay on a rung for a few days, until it feels boring. Boring is the goal.
Before each step, take a slow breath. A minute of breathing for anxiety can calm the body's alarm enough to make the step feel possible. If it helps, do the step with someone you trust sitting next to you.
When you reach rung five, you've done something that is easy to put off for years: you've taken an honest snapshot of your money.
Key takeaway
Start with a 30-second look at one balance. Repeat it until it feels boring, then add one step.
The ladder works better when the environment around it feels less threatening.
Pick a fixed, calm time. Not late at night, not right before something stressful. A morning coffee or a quiet lunch break.
Use a script. Before you look, say to yourself: "This is information, not a verdict. Whatever the number is, I can make a plan for it." It sounds simple, and it helps.
Let alerts do some of the watching. Most banks let you set a low-balance alert and a payment-due reminder. These catch problems early, so you don't have to stay on guard all the time.
Add a small reward. Something pleasant right after you look, like a walk, a favorite song or a good cup of tea, teaches your brain that looking leads somewhere good.
Watch the inner critic. If looking sets off a stream of harsh self-talk, that voice is part of what keeps avoidance going. Our guide to quieting your inner critic has practical ways to answer it.
Key takeaway
Change the setup around money (alerts, timing, words) so looking stops feeling like a test.
Sometimes avoidance has gone on long enough that the practical problems need outside help. Consider reaching out if:
A non-profit credit counseling agency, such as a member of the National Foundation for Credit Counseling (NFCC), can help you sort out debts. A therapist, especially one familiar with financial stress, can help with the anxiety underneath. Asking for help is a way of taking care of yourself.
For most people, though, the first step is small: open your banking app today, look at one balance, and close it. That's all.
When you're ready for the full picture, Day 1 of the 30-Day Money Reset walks you through a gentle Money Snapshot, and Days 1 to 7 are free. The 4-Minute Check is another low-pressure starting point: 12 questions and one clear next step.
Education, not individualized financial or medical advice.
Key takeaway
If avoidance has lasted months or debts are in collections, get help. Otherwise, start with rung one today.
Money avoidance is a pattern of not looking at, thinking about or dealing with money, such as leaving statements unopened, not checking balances, or putting off bills. Researchers who study money beliefs list it as one of four common 'money scripts.'
It often is. Avoidance brings short-term relief from an uncomfortable feeling, and that relief keeps the habit going. If avoidance comes with physical symptoms, poor sleep or constant dread, it is worth treating as anxiety, not as a character flaw.
Your body is reacting to a perceived threat. When money has felt dangerous or shameful before, even opening an app can trigger a stress response. The feeling usually gets weaker with small, repeated, safe exposures.
Start smaller than feels necessary. Open your banking app, look at one balance, and close it. Repeat for a few days, then add one step at a time: recent transactions, then a full week, then a statement.
About the author
Registered Nurse & Mind Wellness Writer
Keep reading
Money goals often fade because they're vague, borrowed or missing a plan for the hard moments. Here's a research-backed way to set one goal, plan for obstacles and see your progress.
Will AI take my job? Is my skill obsolete? Should I even bother? AI anxiety is this decade's fastest-growing worry — part rational signal, part doom spiral. How to separate the two, and the adaptation playbook that beats both denial and despair.
That gut feeling about the job, the relationship, the decision — is it wisdom or fear? Anxiety and intuition speak from the same body but have different signatures. Seven ways to tell them apart before you act.